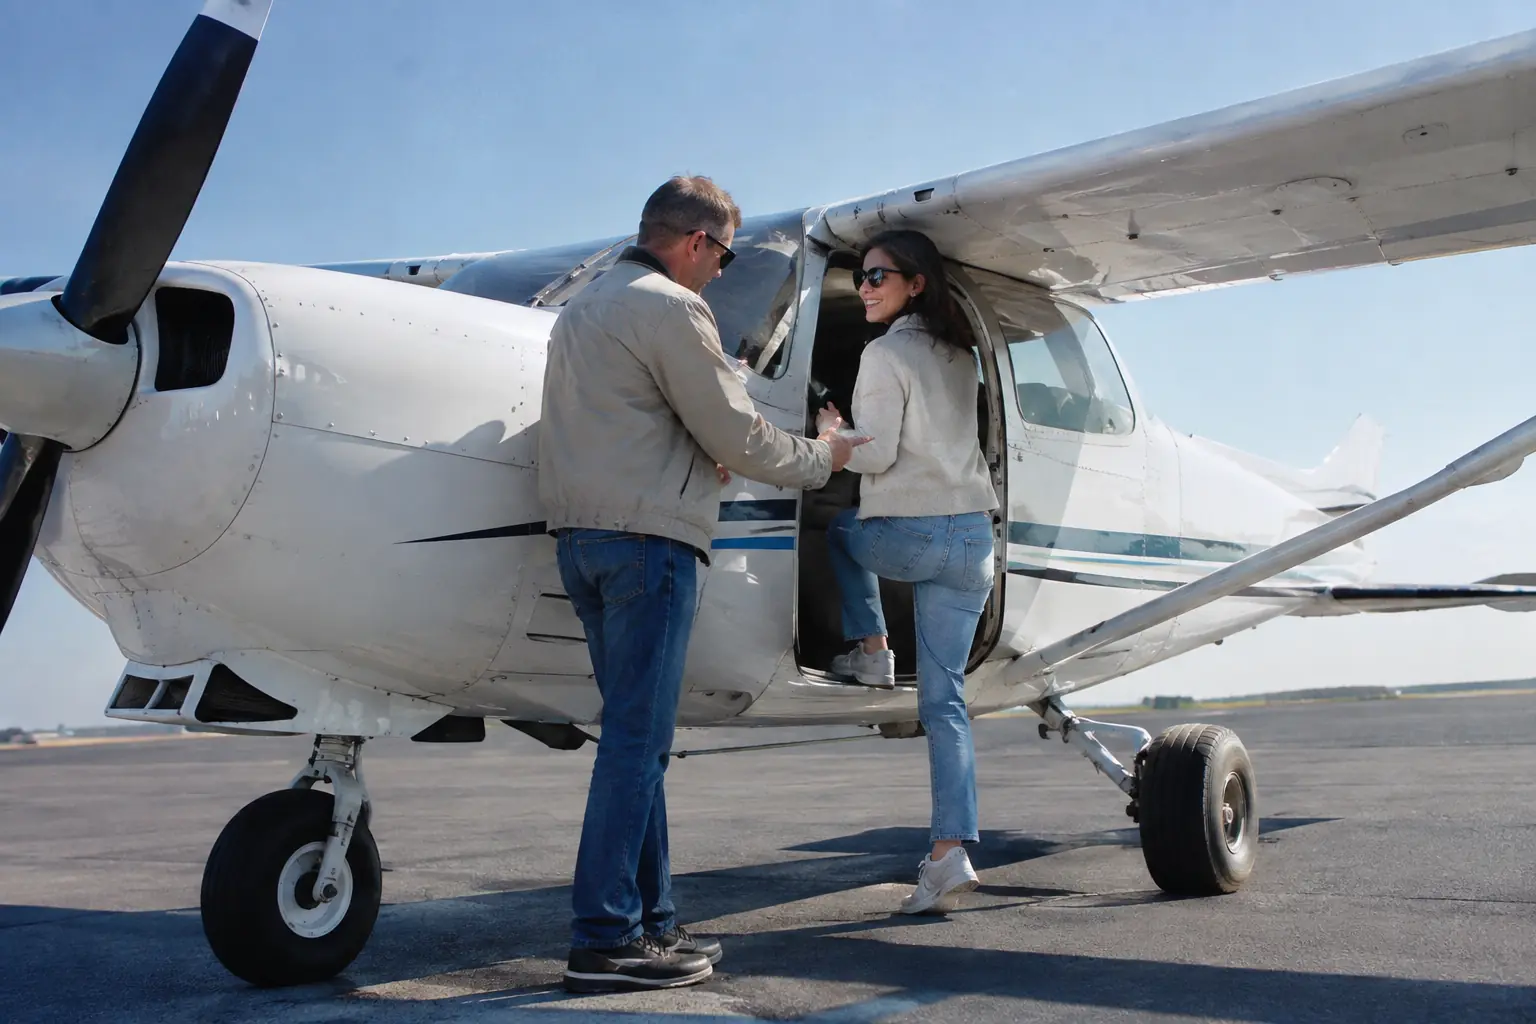
One of the first things most pilots do after getting their certificate is plan a flight with someone they care about. A friend, a parent, a partner who has never been in a small plane. It feels like a natural milestone. But before that passenger climbs in, there is something worth understanding about your aircraft insurance that does not always get spelled out clearly.
Your policy covers you in a lot of scenarios. It may not cover your passenger the way you think it does.
What liability coverage actually does when a passenger is injured
If a passenger in your aircraft is injured during a flight, your owner policy's liability coverage is what responds. It pays for their medical costs, legal defense if they sue you, and any settlement or judgment up to your policy limit. That part most pilots understand. Where things get complicated is in how those limits are structured.
Many single-engine aircraft insurance policies are written with a Combined Single Limit, or CSL. A $1 million CSL means that $1 million is the total amount available for any single occurrence, split across everyone involved: third parties on the ground, your passenger, property damage. There is no separate bucket reserved just for your passenger.
Some policies also offer per-seat sub-limits. A policy might read $1 million CSL with $100,000 per seat. That sub-limit can be the binding number if a passenger's claim exceeds it, even if the total policy limit is much higher. In a serious injury situation, $100,000 does not go far. Understanding which structure your policy uses matters before you ever take off with someone beside you.
Passengers vs. third parties: not the same thing
Your liability coverage treats a person injured on the ground differently from someone sitting in your right seat. Third-party liability is generally straightforward. If you damage property or injure someone unrelated to your flight, your policy responds to their claim up to your limit.
For passengers, the dynamic is a bit different. General aviation policies do cover passenger injury liability. But some older or bare-bones policies have exclusions worth looking at, particularly around guest passengers and voluntary activities. The language varies by policy. If you are flying someone frequently and have never actually read your passenger liability section, that is worth fifteen minutes of your time.
What your policy does not cover for passengers
Your aircraft insurance is not health insurance. It does not pay your passenger's medical bills proactively. It responds to claims, which means coverage is triggered when someone makes a formal demand or files suit against you. If your passenger is injured and simply goes to the hospital, your policy does not automatically reimburse their costs. They would need to pursue a claim against you.
Some pilots assume their policy works like a medical payments provision in auto insurance, which pays regardless of fault. Most aviation policies do not work that way. If your passenger has their own health insurance, that pays first. Your liability coverage becomes relevant if they seek compensation from you above and beyond what their own insurance handles, or if they allege negligence.
There is also no coverage for any passenger who is flying for compensation or hire under a standard Part 91 owner policy. Taking money for the flight changes the nature of the operation and voids that coverage entirely.
Checking your limits before the flight makes sense
If you regularly fly with passengers, it is worth reviewing your liability limit in the context of what a serious aviation injury claim could cost. A straightforward hospitalization can run into six figures. A wrongful death or permanent disability case often reaches into seven. Most pilots flying friends and family carry at least $1 million per occurrence, and many choose more, particularly if they have significant personal assets.
The premium difference between $1 million and $2 million in liability coverage is usually modest on a light aircraft policy. Reviewing those numbers once a year, when your policy renews, is one of the simpler things you can do to make sure your coverage still fits how you are actually flying. You can get a quick look at your options at skywatch.ai.
Frequently asked questions
Does my aircraft owner insurance automatically cover passengers?
Yes, liability coverage in a standard owner policy covers passenger injury claims. But coverage is triggered by a claim against you, not automatically. Your passenger's medical costs are not paid proactively by your policy.
What is the difference between a CSL and a per-seat limit?
A Combined Single Limit (CSL) is the total available for all claims from one occurrence. A per-seat sub-limit caps what is available specifically for any one passenger. If your policy has a $1 million CSL with a $100,000 per-seat sub-limit, a badly injured passenger could only claim up to $100,000 from your policy, even though your total limit is higher.
Can I charge passengers for a flight under my owner policy?
No. Standard Part 91 owner policies do not cover flights where passengers pay for the trip. Taking compensation for a flight changes the legal classification of the operation and removes your coverage. Flying under a pro-rata cost-sharing arrangement has its own rules and is worth confirming with your insurer.
How much passenger liability coverage do most aircraft owners carry?
$1 million per occurrence is a common baseline for light aircraft owners who fly with passengers. Pilots with higher personal net worth or who fly frequently with passengers often carry $2 million or more. The premium difference is typically small relative to the increased protection.
Does my passenger need their own insurance?
Your passenger does not need aviation insurance. But they should understand that your owner policy covers claims made against you, not their out-of-pocket expenses. If they are injured and their own health insurance covers their costs, the situation may resolve without involving your liability coverage at all.