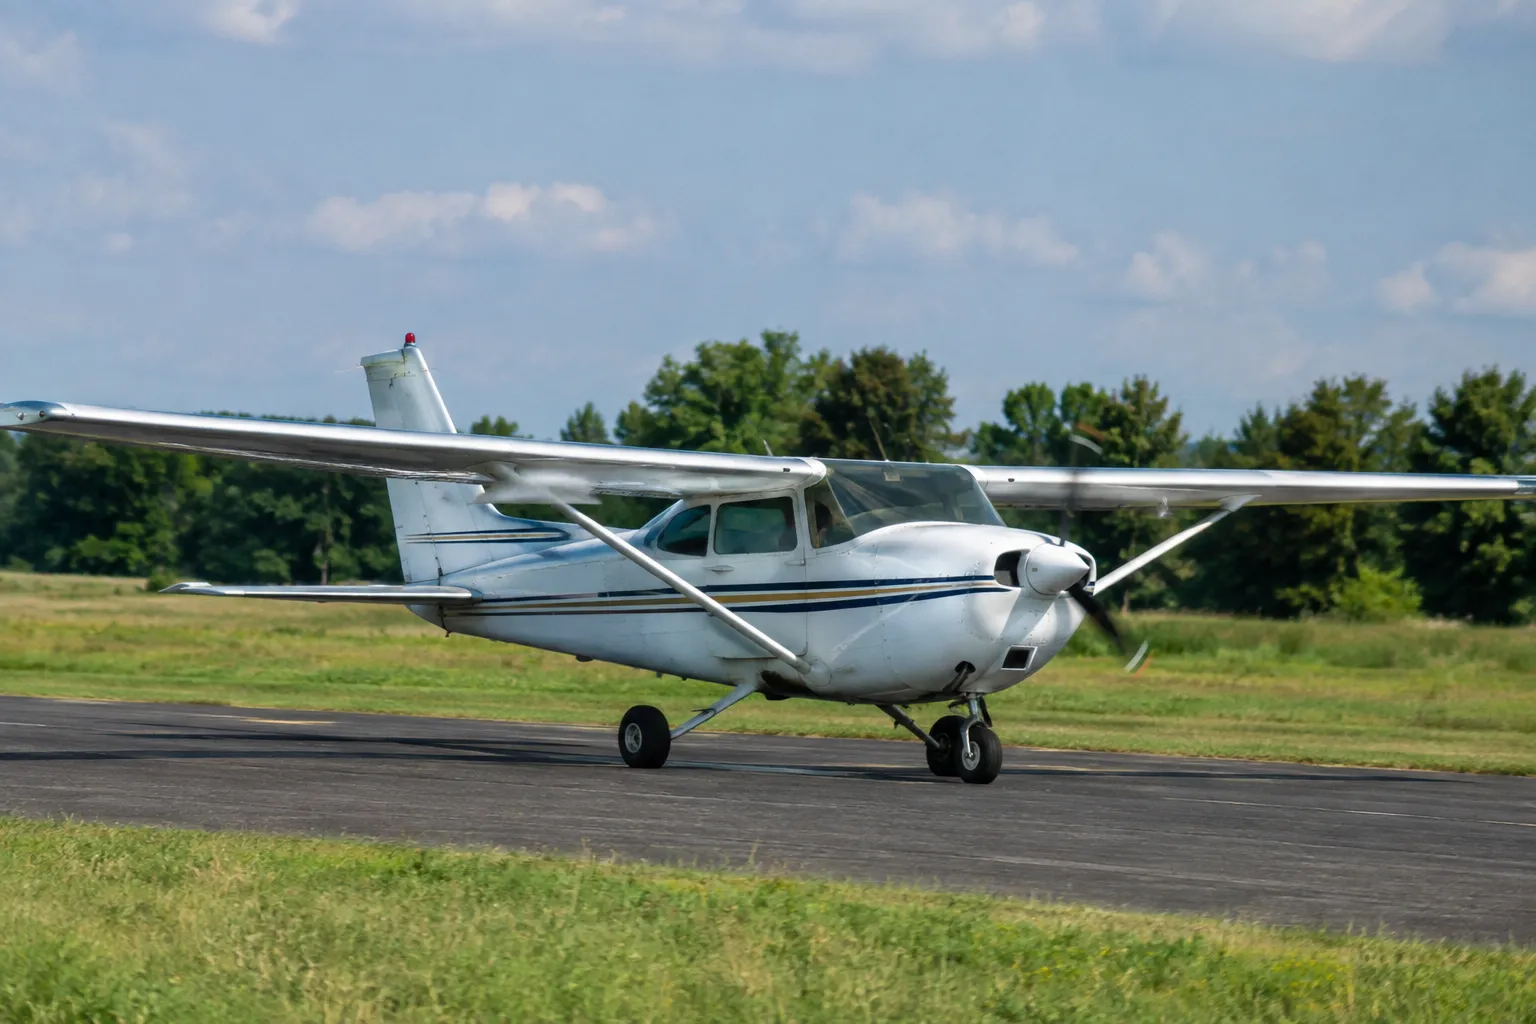
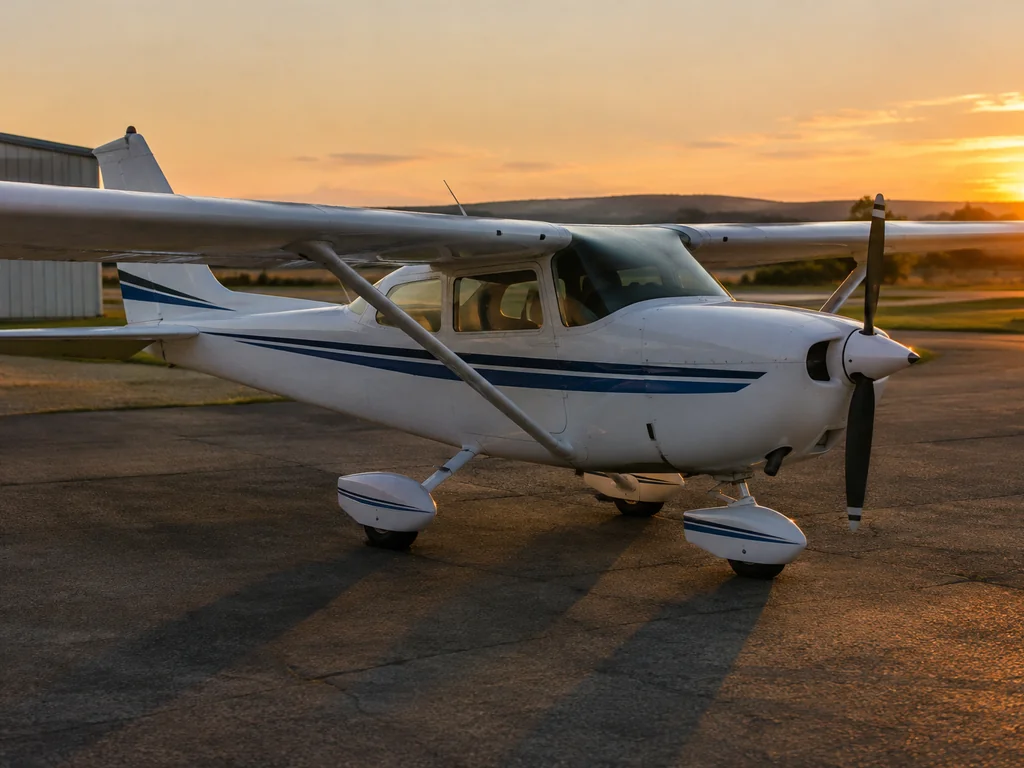
You took a year off. Maybe three. Work got busy, a kid arrived, or the money went elsewhere. Now you want to rent a Cessna 172 on a Saturday morning and remember why you fell for flying in the first place.
Before you book the plane, it helps to know that time away changes how the FBO, the law, and your insurance look at you.
Legal currency and insurance currency are different things
The FAA has its own rules. A flight review every 24 calendar months under FAR 61.56. Three takeoffs and landings in the previous 90 days to carry passengers under FAR 61.57. A valid medical or BasicMed, depending on how you fly.
Insurance adds another layer. Policies can include pilot requirements such as recent hours, a flight review, or a checkout in the aircraft you plan to fly. Meeting the FAA minimum does not automatically mean you meet your policy's conditions. Read the pilot warranty section before you fly, not after.
Expect a checkout, even in a plane you know
Most FBOs and flight schools want to see you fly before they hand over the keys, especially if your logbook has a gap. Our guide to FBO checkout procedures walks through what that usually looks like. Some places ask for an hour with an instructor. Others want a few landings. It varies by operator, and it is often tied to their own insurance requirements.
Do not treat it as a hurdle. A rusty pilot in a familiar-looking airplane is exactly the situation where an instructor in the right seat earns the fee.
The FBO's insurance is not your insurance
Rental operators carry coverage on their aircraft, but that policy is built to protect the operator. It may not cover your liability to others in the way you assume, and you may be responsible for a deductible or for damage in some situations. We covered the details in our post on non-owned aircraft insurance coverage limits. Ask the operator for their rental agreement and read what you are on the hook for.
Coming back is a good time to buy short-term coverage
If you only plan to fly a few times while you rebuild your hours, a full annual policy may be more than you need. SkyWatch aircraft renters insurance is offered on flexible terms, including daily, weekly, monthly or annual options, so you can match coverage to how often you actually fly. Eligibility and terms depend on your experience and the aircraft, so check them before you count on coverage.
A simple plan for your first flight back
Check your medical and flight review dates. Call the FBO and ask what they require for someone returning after a break. Confirm what your insurance expects for hours and checkout. Then book an instructor for the first flight, even if you could legally fly alone.
FAQ
Do I need a flight review before renting after a long break?
If your last flight review is more than 24 calendar months old, FAR 61.56 requires one before you act as pilot in command. Many rental operators will want to fly with you first regardless.
Does my old non-owned policy still apply if it lapsed?
A lapsed policy does not cover flights after it ended. Check the dates on your policy and the terms for renewing or buying new coverage.
Can the FBO refuse to rent to me even if I am legal?
Yes. Operators set their own requirements, often because of their insurance. Being legally current does not guarantee they will rent to you.
Do I need insurance if the FBO already insures the plane?
The operator's policy is designed to protect the operator. Many renter pilots add their own non-owned coverage for their personal liability and to address gaps in what the rental agreement makes them responsible for.
Can I get short-term renters insurance while I rebuild my hours?
SkyWatch offers daily, weekly, monthly and annual options. Whether you qualify depends on your experience and the aircraft you plan to fly.